Introduction
Life insurance cost depends on several key factors, and understanding them helps you find affordable protection. Most people don't lie awake wondering about premiums. They lie awake wondering what happens to their family if they're not around to provide. The honest answer is that the financial gap left behind can be devastating — mortgages don't pause for grief, and college tuition doesn't wait for families to recover.
Here's what that actually means in practical terms: a healthy 35-year-old earning $90,000 annually with a $280,000 mortgage and two children might need $500,000 to $1 million in coverage to replace income, pay off debt, and fund future education costs. The math works like this — if you're the primary earner and you disappear tomorrow, your family needs enough to maintain their standard of living, clear major debts, and cover the expenses you would have handled over the next 20 to 30 years.
The framework for calculating that coverage gap starts with your existing financial obligations and works forward. A common misconception is that single people with no dependents don't need coverage at all. If you've co-signed a student loan with a parent or sibling, that debt doesn't vanish when you do — it becomes their problem. The goal is getting in the right range of protection, not achieving some perfect number that doesn't exist.
When considering life insurance cost, age plays a significant role — younger individuals typically pay less because they pose lower risk to insurers. The type of policy also affects cost. Term life insurance is often more affordable than permanent life insurance, which includes a cash value component. Understanding these nuances helps in making informed decisions about your specific situation.
What Drives the Numbers
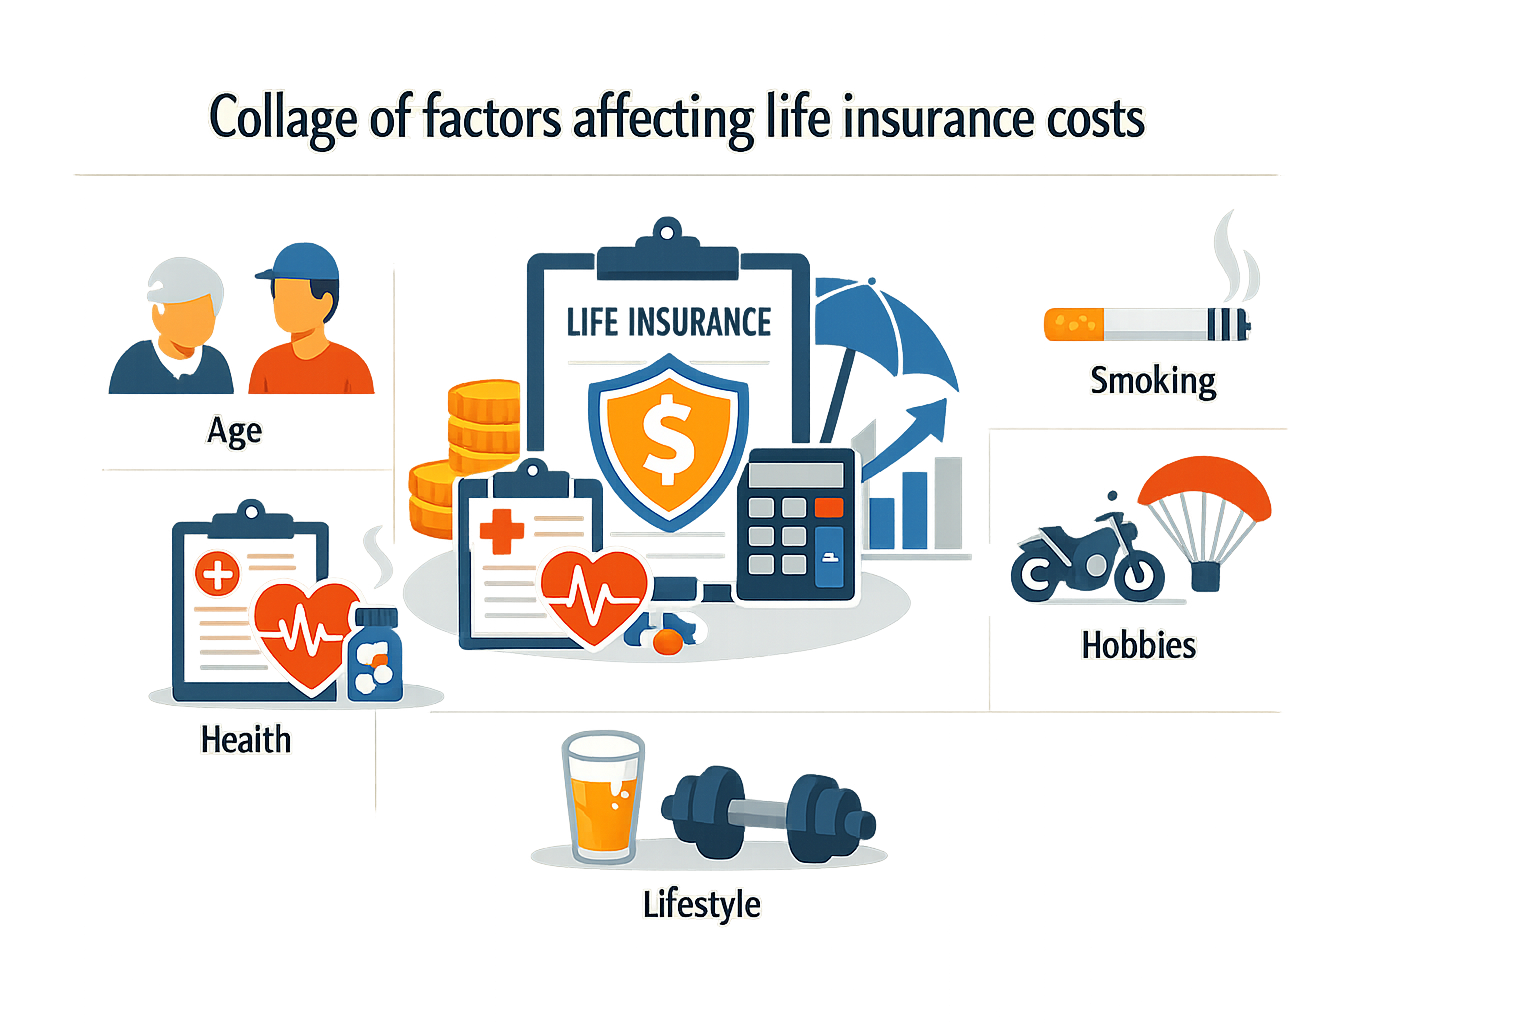
The short answer to what you'll actually pay depends on factors you control and factors you don't. Age is the biggest driver — a 30-year-old pays a fraction of what a 50-year-old pays for identical coverage because actuarial tables don't lie about mortality risk. Health status comes next. If you're a non-smoker with normal blood pressure and no family history of heart disease, you'll pay less than someone with diabetes or a smoking habit.
Policy type creates the widest cost spread. A 20-year term policy with a $500,000 death benefit might cost a healthy 35-year-old $25 to $40 per month. The same death benefit in a whole life policy could run $400 to $600 monthly. The difference isn't arbitrary — term insurance covers you for a set period and pays out only if you die during that window, while permanent policies build cash value and last your entire life if you keep paying premiums.
Coverage amount scales the premium in a straightforward way. Double the death benefit, and you roughly double the cost. The difference between $250,000 and $500,000 in term coverage for that same 35-year-old might be $15 per month — worth understanding when you're deciding how much protection your family actually needs.
This article breaks down the real costs you'll encounter, the factors that move your premium up or down, and the practical steps to get coverage that fits your budget without leaving your family exposed. For informational and educational purposes, not as personalized financial advice — when you're ready to take the next step, talk to a licensed financial professional about your circumstances.
Understanding the Costs of Life Insurance
Most people approach life insurance with one of two misconceptions: either they think it's prohibitively expensive, or they assume the price is fixed and non-negotiable. Neither is accurate. The real question is understanding what drives the number on your quote and why two people applying for the same coverage amount can see wildly different premiums.
The framework for pricing life insurance isn't mysterious — insurers are calculating risk. They're asking: How likely is this person to die during the coverage period, and what will it cost us if they do? Age is the most obvious factor. A 30-year-old poses less risk than a 55-year-old, so premiums reflect that difference. But age is just the starting point. Health status, family medical history, occupation, and lifestyle choices all feed into the actuarial model.
A common misconception is that life insurance is a one-size-fits-all product with standardized pricing. In practical terms, two applicants requesting $500,000 in term coverage might see quotes that differ by hundreds of dollars annually based on health class alone. Someone in "preferred plus" health (non-smoker, excellent health metrics, no family history of early heart disease) pays substantially less than someone in "standard" health with controlled high blood pressure.
Why Understanding Cost Matters
The difference between understanding and guessing at life insurance cost isn't academic — it directly affects whether families get the coverage they need. When people overestimate the price, they either skip coverage entirely or buy far less than their dependents would need. When they underestimate, they're unprepared for the underwriting process and may be surprised by higher-than-expected premiums.
The math works like this: if you assume term life insurance will cost $200 per month and discover it's actually $75, you might increase your coverage amount or extend the term length to better protect your family. If you assume it's $50 and it's actually $150, you might reduce coverage to fit your budget — potentially leaving a gap. Worth understanding before you apply.
The cheapest policy is worthless if it doesn't cover the actual financial gap your family would face.
Another factor most people don't realize: the type of policy fundamentally changes the cost structure. Term life insurance premiums are straightforward — you're paying for pure death benefit coverage over a set period. Permanent life insurance (whole life, universal life) includes a cash value component and lifetime coverage, which is why premiums are significantly higher. The difference isn't a markup; it's a different product solving a different problem.
For informational and educational purposes, it's also worth noting that policy transfers can have tax implications. If you purchase an existing policy from someone else rather than applying for new coverage, the taxable amount you'd receive at payout may differ from a standard policy — a detail that affects the true cost of ownership in certain estate planning scenarios.
Understanding these cost drivers gives you a realistic starting point when you're ready to take the next step. The goal isn't finding the absolute cheapest premium; it's getting in the right range for coverage that actually protects your family's financial stability.
Breaking Down Life Insurance Costs
Life insurance cost breaks down into several distinct components. Understanding each one helps you see where your premium dollars go and why two people of different ages or health profiles pay different amounts.
The Core Pricing Factors
Insurers calculate premiums using a mortality table — a statistical model that predicts how long people in different age groups are likely to live. Your age at application is the starting point. A 30-year-old pays less than a 50-year-old for the same coverage because the younger applicant statistically has more years ahead. The math is straightforward: lower risk of a near-term claim means a lower premium.
Health status follows age as the second major factor. During underwriting, the insurer reviews your medical history, current conditions, prescription use, and sometimes requests lab work or an exam. Someone with well-controlled high blood pressure might pay slightly more than someone with no conditions, but the difference is often smaller than most people expect. Serious or unstable conditions can push premiums higher or, in some cases, make coverage unavailable through traditional underwriting.
Step 1
Age and mortality risk
Younger applicants receive lower premiums because actuarial tables show longer life expectancy. The age of the youngest insured individual plays a crucial role in determining the premiums for life insurance contracts that cover multiple lives — when a policy insures two people on a last-to-die basis, the insurer uses the younger person's age as the baseline for pricing.
Step 2
Health and underwriting class
Your health profile determines your underwriting class — typically preferred plus, preferred, standard plus, or standard. Each class corresponds to a different premium tier. The insurer looks at weight, blood pressure, cholesterol, glucose levels, family history, and lifestyle factors like tobacco use. Non-smokers in excellent health qualify for the lowest rates.
Step 3
Coverage amount and term length
The face amount — how much the policy pays when you die — directly affects cost. A $500,000 policy costs more than a $250,000 policy, all else equal. For term life insurance, the length of the term also matters. A 20-year term costs more per year than a 10-year term because the insurer is on the hook for a longer period, and you'll be older (and statistically closer to a claim) in the later years.
Step 4
Policy type and riders
Term life insurance costs less than permanent life insurance because it has no cash value component and covers a defined period. Permanent policies — whole life, universal life, variable life — include a savings or investment element that builds cash value over time, which increases the premium. Adding riders like accelerated death benefit, waiver of premium, or a child term rider also adds to the base cost.
Gender and Occupation
Women typically pay less than men for the same coverage at the same age because women statistically live longer. The difference is usually modest but consistent across age groups. Occupation and hobbies can also influence pricing. If you work in a high-risk profession — commercial fishing, logging, roofing — or engage in activities like skydiving or rock climbing, the insurer may apply a surcharge or exclude certain causes of death.
How Insurers Calculate the Final Number
Once the insurer collects all the data — age, health, coverage amount, term length, policy type — they run it through their pricing model. The model uses mortality assumptions, administrative costs, profit margin, and investment income projections to arrive at a premium. Different insurers use different models, which is why the same applicant can receive different quotes from different companies. Shopping around is worth the effort.
The premium you see in a quote is the annual cost, though most insurers let you pay monthly. Monthly payments usually include a small billing fee, so paying annually saves a bit over the long run. The premium stays level for the entire term in a level term policy — your year-one cost is the same as your year-20 cost.
Tips for Lowering Life Insurance Premiums
Most people assume life insurance cost is fixed once they get a quote. The real question is whether you're paying for coverage that matches your actual needs or overpaying for features you don't use.
Buy coverage when you're younger and healthier
Premiums lock in at the rate you qualify for when the policy starts. A healthy 30-year-old pays significantly less than a 45-year-old for the same coverage amount and term length. Waiting until a health issue surfaces can push you into a higher risk class or make coverage unaffordable.
The math works like this: every year you delay, your age increases and your statistical risk to the insurer goes up. If you know you need coverage, applying sooner rather than later keeps your premium lower for the entire term.
Choose term life insurance for straightforward protection
Term policies cost less because they cover a specific period without building cash value. If your goal is replacing income or covering debts during your working years, term life insurance delivers the coverage you need at a fraction of permanent policy premiums.
Permanent policies — whole life or universal life — include an investment component that increases the cost. For most families, separating insurance from investing makes more sense: buy term coverage for protection and invest the difference in retirement accounts or other vehicles.
Compare quotes from multiple carriers
Each insurer uses its own underwriting guidelines and risk models. One company might rate your blood pressure as standard while another offers preferred rates. Shopping around doesn't cost anything, and the difference between quotes can be 20 to 30 percent for identical coverage.
Work with an independent agent who can pull quotes from several carriers at once. They see which companies are competitive for your age, health profile, and coverage amount without requiring you to apply multiple times.
The cheapest policy is the one that actually pays when your family needs it — focus on financial strength ratings and claim-paying history, not just premium.
Lock in longer terms to avoid reapplying
A 20-year or 30-year term costs more per year than a 10-year term, but it protects you from needing to requalify when the shorter term ends. If your health declines or you develop a condition during that first decade, renewing or buying new coverage becomes expensive or impossible.
The goal is getting in the right range: long enough to cover your dependents until they're self-sufficient, but not so long that you're paying for coverage you won't need. Most families align term length with mortgage payoff or the year their youngest child finishes college.
Improve your health before applying
Underwriting looks at weight, blood pressure, cholesterol, and tobacco use. Losing 15 pounds, quitting smoking, or managing a chronic condition can move you into a better rate class. Insurers typically require 12 months of tobacco-free status to qualify for non-smoker rates, so plan ahead if you're working on quitting.
Some carriers offer re-evaluation riders that let you request a rate reduction after the policy is in force if your health improves. Not all policies include this, so ask upfront if it's available.
Understand how policy transfers affect taxation
If you're considering buying an existing policy from someone else — a life settlement or transfer — the tax treatment changes. The amount you can exclude from gross income when the policy pays out is limited to what you paid for the policy plus any premiums you contributed afterward. Anything above that is taxable.
This matters because it can reduce the net benefit your beneficiaries receive. For informational and educational purposes, the IRS rules on transferred policies are detailed and worth reviewing with a tax professional if you're exploring this route.
Pay annually instead of monthly
Most insurers charge a processing fee for monthly payments, which adds 3 to 5 percent to your annual cost. Paying the full premium once a year eliminates those fees. If cash flow is tight, some carriers offer quarterly or semi-annual payment schedules that split the difference.
The framework: if you can afford the lump sum without stress, annual payment is the most cost-effective option. If not, monthly works fine — just know you're paying a small convenience premium.
Conclusion
The short answer to life insurance cost depends on your age, health, coverage amount, and policy type. A healthy 35-year-old might pay $30 to $50 per month for a 20-year term policy with $500,000 in coverage, while a 50-year-old with similar coverage could pay $150 to $250 monthly. Permanent policies cost significantly more because they build cash value and last your entire life.
What matters most is getting in the right range for your situation. If you're earning $90,000 annually with a $280,000 mortgage and two children, a term policy covering 10 to 15 times your income makes sense — the math works out to roughly $900,000 to $1.35 million in coverage. That might sound like a lot, but the monthly premium stays manageable because term insurance focuses purely on the death benefit without the investment component of permanent coverage.
Understanding these nuances helps in making informed decisions about life insurance. Even if you're single with no dependents, consider whether anyone has co-signed a loan with you — that debt could become their responsibility if something happens to you. The framework isn't complicated once you know what drives the numbers: age, health status, policy length, and coverage amount account for most of the variation in premiums.
When you're ready to take the next step, talk to a licensed financial professional who can run quotes based on your specific situation. For more guidance on choosing the right coverage amount, see how much life insurance you need. The goal is protecting the people who depend on your income without overpaying for features you don't need.
FAQ
How is life insurance cost calculated?
Life insurance cost is calculated based on your age, health status, coverage amount, policy type, and term length. Insurers use mortality tables and underwriting data to assess risk and set premiums accordingly.
What factors affect life insurance cost the most?
Age and health are the biggest factors affecting life insurance cost. Younger, healthier applicants pay lower premiums. Policy type (term vs. permanent) and coverage amount also significantly impact cost.
How much does life insurance cost per month on average?
A healthy 35-year-old might pay $30-$50 monthly for $500,000 in 20-year term coverage. A 50-year-old with similar coverage could pay $150-$250 monthly. Permanent policies cost significantly more.
Discover what life insurance cost really looks like by age, health, and policy type. Get realistic premium breakdowns and tips to lower your rates.
Related reading
Roth IRA or 401k: Which Should You Fund First?